South Florida Home Insurance 2026:
South-Florida-Home-Insurance-Guide-2026
The Number Most South Florida Buyers Get Wrong
I have been selling real estate in South Florida for ten years. And the single most common mistake I see buyers make — especially buyers relocating from other states — is underestimating the cost of homeowners insurance.
They budget for the mortgage. They budget for the property taxes. They forget about the insurance.
In South Florida in 2026 that is a very expensive mistake. Let me give you the real numbers before you make an offer on any property in this market.
⚡ The Reality — South Florida Insurance Costs in 2026
South Florida Average (Inland) $4,375 – $5,500 per year
South Florida Average (Coastal) $5,500 – $8,300+ per year
Monthly Impact (inland) $365 – $458 per month added to your payment
Monthly Impact (coastal) $460 – $692+ per month added to your payment
Florida vs National Average Florida: $4,300–$8,458/yr vs National: $2,580/yr
Citizens Rate Cut 2026 8.7% statewide · 11.9%–14.1% in Miami-Dade
Wind Mitigation Savings 20–45% reduction on windstorm portion of premium
Wind Mitigation Inspection Cost $100–$150 — one of the best investments a buyer can make
Hurricane Deductible Typically 2–10% of home value — separate from standard deductible
Flood Insurance NOT included in standard homeowners policy — separate cost
Why South Florida Insurance Costs So Much
Florida homeowners insurance is the most expensive in the United States — and South Florida is the most expensive region within Florida. Understanding why helps you make smarter buying decisions.
Hurricane Risk
The primary driver of South Florida insurance costs is hurricane exposure. Miami-Dade County sits in one of the highest hurricane risk zones in the country — and that risk is priced into every policy. The windstorm portion of your premium alone can represent 40 to 55 percent of your total insurance cost.
Roof Age and Condition
In South Florida, your roof is one of the most important factors in determining your insurance cost and insurability. Homes with roofs older than 15 years face dramatically higher premiums — and some carriers will not insure them at all. Homes built before 2002 — before Florida's strengthened building codes took effect after Hurricane Andrew — are also significantly more expensive to insure.
Before making an offer on any South Florida home — ask for the roof age and condition report. This is non-negotiable.
Insurer Exits and Market Instability
Over the past several years numerous major national insurers reduced or eliminated Florida homeowners coverage, leaving many homeowners dependent on Citizens Property Insurance — the state-backed insurer of last resort. While the market has stabilized significantly in 2026 and Citizens has cut rates by an average of 8.7% statewide, it is important to understand that the Florida insurance market remains more volatile than most other states.
The Good News — 2026 is a Better Year
For the first time in over a decade the Florida homeowners insurance market is genuinely stabilizing. Citizens Property Insurance announced an average 8.7% rate cut statewide for 2026 — with Miami-Dade and Broward counties seeing cuts of 11.9% to 14.1%. State Farm, AAA, Florida Peninsula, and Universal all filed rate decreases for 2026.
This does not mean insurance is cheap. It means the era of 40% annual increases has paused — and for buyers entering the South Florida market in 2026 the timing is better than it has been in years.
Sandra's Rule — Get Your Insurance Quote Before You Make an Offer
I tell every buyer I work with the same thing: get an insurance quote before you fall in love with a property. Not after. Before.
Here is why. I have seen buyers get emotionally attached to a home, make an offer, go under contract — and then discover that the insurance cost makes the total monthly payment unworkable. At that point they either have to walk away and lose their deposit, or accept a payment they cannot afford.
A $5 insurance quote before you write the offer saves you from that situation entirely.
The Wind Mitigation Inspection — The Best $125 a Buyer Can Spend
A wind mitigation inspection (officially called OIR-B1-1802) is a $100 to $150 inspection that documents the wind-resistant features of a home — roof shape, roof-to-wall connections, opening protections, and other factors that reduce the risk of hurricane wind damage.
The result: a reduction of 20 to 45 percent on the windstorm portion of your premium. On a $6,000 annual premium where windstorm represents 50% — that is a $600 to $1,350 annual savings. Every year. The inspection pays for itself many times over.
Request a wind mitigation inspection on every South Florida home you seriously consider purchasing.
Understanding Your Deductibles
Standard Deductible
Your standard homeowners deductible works like any other insurance — you pay the deductible amount when you make a claim, the insurance company pays the rest. Common amounts are $1,000 to $5,000.
Hurricane Deductible — This is the One to Watch
Florida policies carry a SEPARATE hurricane deductible — and this is the one that surprises buyers from other states. The hurricane deductible is typically calculated as a PERCENTAGE of your home's insured value — commonly 2% to 10%.
On a $600,000 home with a 2% hurricane deductible — you absorb the first $12,000 of hurricane wind damage before insurance pays anything. At 5% — that is $30,000. At 10% — $60,000.
This is not a reason not to buy. But it is a reason to have an emergency fund and to understand exactly what your policy covers before a storm.
Flood Insurance — The Separate Policy Most Buyers Forget
Standard homeowners insurance does NOT cover flood damage. In South Florida — where heavy rain events and hurricane storm surge are very real risks — flood insurance is essential for most properties.
Flood insurance is available through the National Flood Insurance Program (NFIP) or through private flood insurance carriers. The cost depends heavily on your property's flood zone designation — properties in higher-risk flood zones (Zone AE, Zone VE) pay significantly more than properties in lower-risk zones.
Before making an offer on any South Florida property — check the flood zone designation at msc.fema.gov and get a flood insurance quote. This is another cost that surprises buyers who are not used to South Florida.
What to Look For in a South Florida Home to Minimize Insurance Cost
• New or newer roof — ideally less than 5 years old. Metal roofs receive the best insurance ratings.
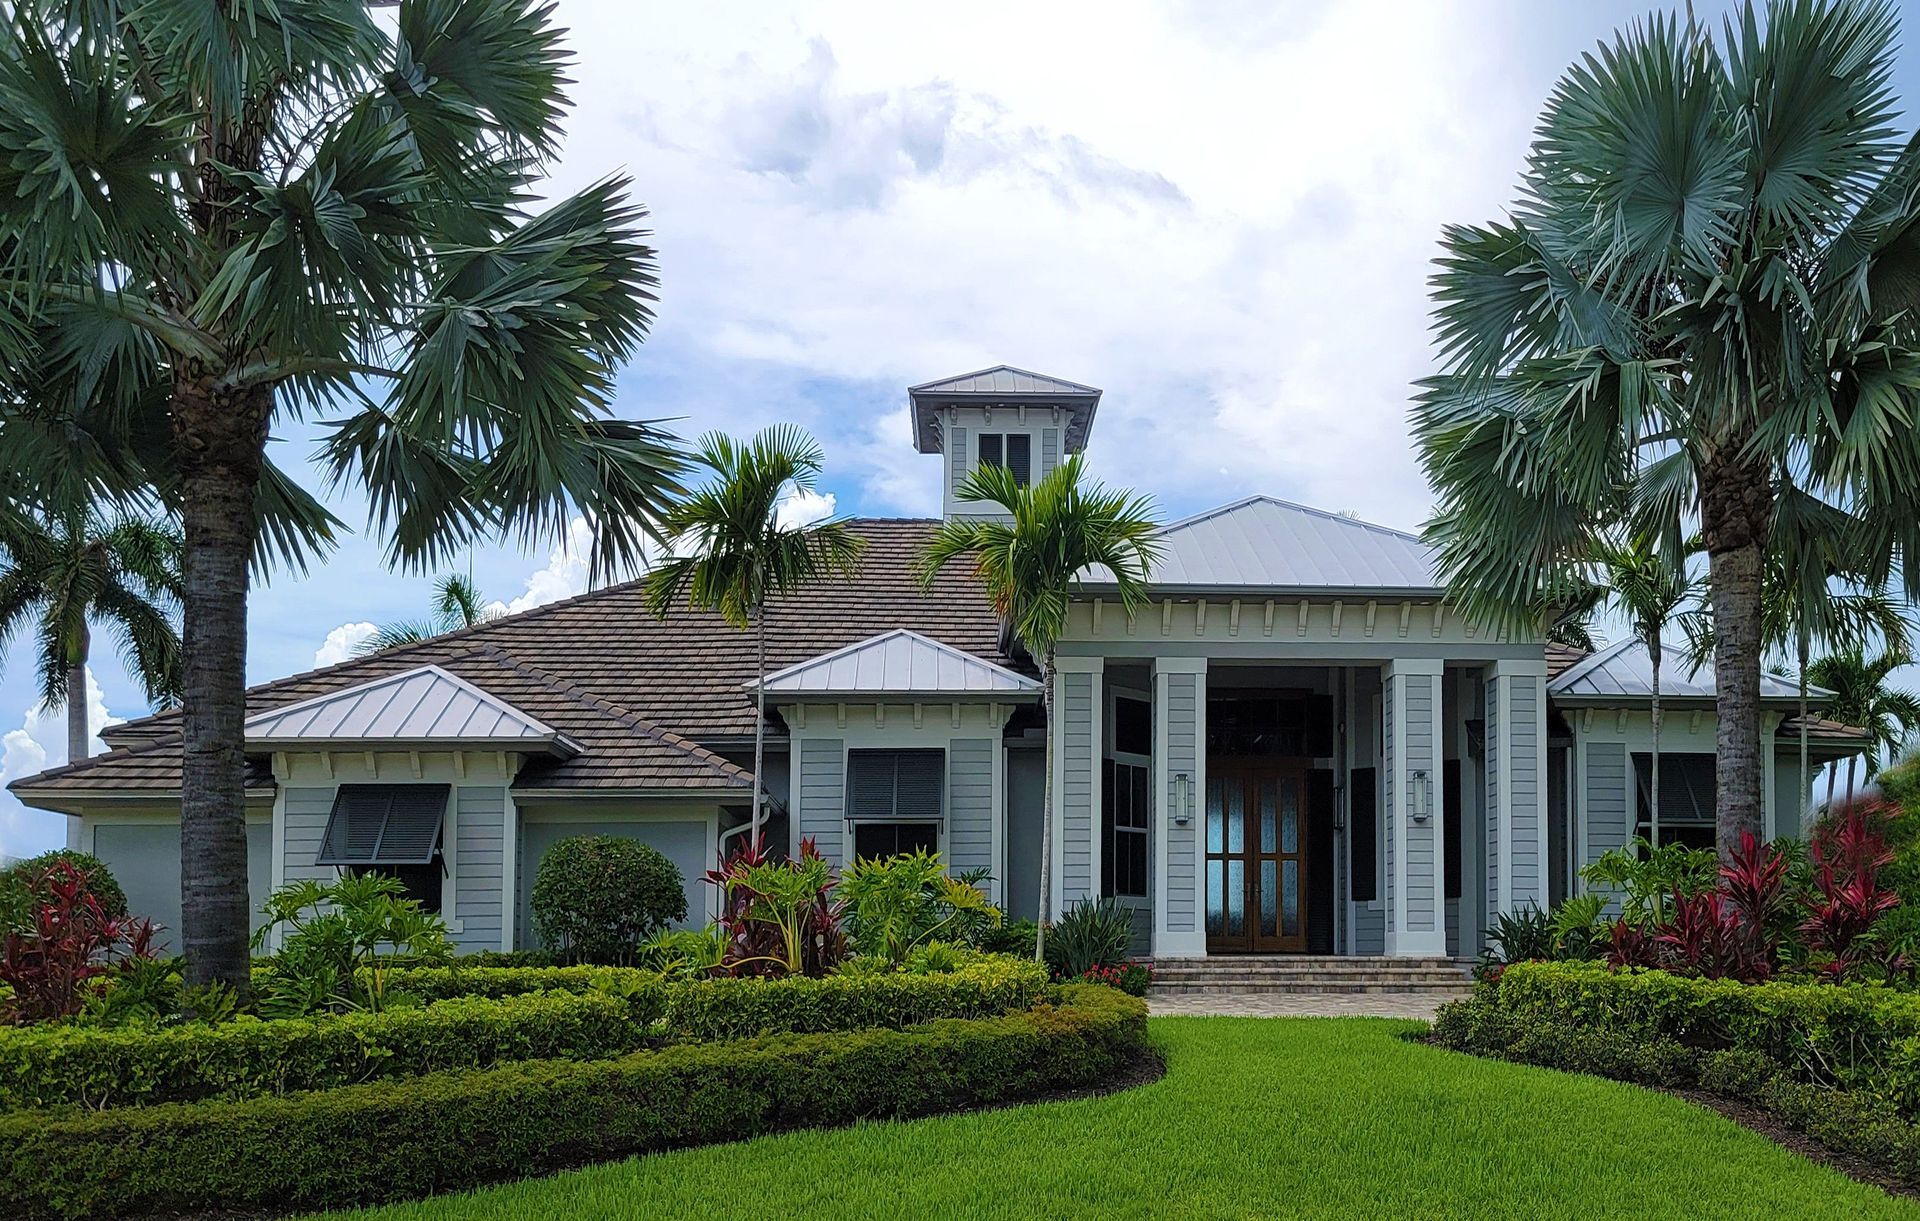
• Hip roof shape (all sides slope down) rather than gable roof (two-sided triangle). Hip roofs are significantly more wind-resistant.
• Hurricane impact windows and doors — provides substantial premium discounts.
• Storm shutters — accordion shutters, panel shutters, or roll-down shutters.
• Post-2002 construction — built to Florida's strengthened building codes after Hurricane Andrew.
• Not in a high-risk flood zone — check FEMA flood maps before making an offer.
• No prior claims history — a home with multiple prior claims will be significantly more expensive to insure.
Budget Reality for South Florida Buyers in 2026
Here is what I tell every buyer to budget for insurance based on their situation:
Newer inland single family home (post-2002, good roof):
$3,500 to $5,000 per year — approximately $290 to $415 per month.
Older or coastal single family home:
$5,500 to $8,000+ per year — approximately $460 to $670+ per month.
Condominium (HO-6 policy):
Generally less expensive individually — typically $1,200 to $2,500 per year for your unit contents and interior coverage. However, note that master policy cost increases pass through your HOA dues — so the full cost is not always visible in your individual policy.
My Honest Advice
South Florida insurance costs are real, meaningful, and must be factored into every buying decision. They are not a reason not to buy here — but they are absolutely a reason to do your homework before you fall in love with a property.
Get the insurance quote first. Check the roof age. Understand the hurricane deductible. Check the flood zone. Get the wind mitigation inspection.
And then make your decision with complete information.
That is what I walk every buyer I work with through — and it is the difference between a purchase you feel great about and a purchase that surprises you after closing.
If you have questions about buying in South Florida — I am always available at 305-613-3376. Call me.
📚 Related Reading
How to Buy a Home in Cutler Bay — Step by Step Guide https://www.homesbysandraalonso.com/blog/how-to-buy-home-cutler-bay
First Time Home Buyer Guide — South Florida 2026 https://www.homesbysandraalonso.com/blog/first-time-home-buyer-guide-south-florida
How to Win a Bidding War in South Florida https://www.homesbysandraalonso.com/blog/how-to-win-bidding-war-south-florida
Relocating to South Florida — The Complete Honest Guide https://www.homesbysandraalonso.com/blog/relocating-to-south-florida-2026
Cash vs Financing in South Florida — What You Need to Know https://www.homesbysandraalonso.com/blog/cash-vs-financing-south-florida
About the Author
Sandra K. Alonso REALTOR® · Brown Harris Stevens
Sandra Alonso is a South Florida native and ten-year real estate veteran specializing in Coral Gables, Palmetto Bay, Cutler Bay, Pinecrest, and South Miami. As a 21-year original owner at Cutler Cay and a bilingual English/Spanish agent with Brown Harris Stevens, Sandra brings authentic hyperlocal knowledge to every buyer and seller she represents.
📞 305-613-3376 ✉️ salonso@bhsusa.com 🌐 www.homesbysandraalonso.com
Sources and References
• Insurify — Florida homeowners insurance 2026 data · insurify.com
• Citizens Property Insurance Corporation — 2026 rate filings · citizensfla.com
• Florida Office of Insurance Regulation — floir.com
• FEMA Flood Map Service Center — msc.fema.gov
• EZ Funding Online — Florida home insurance buyer's guide 2026
• Calclogix — Florida homeowners insurance crisis 2026 complete guide